Specialty financing for real estate investors
40-Year DSCR Loans
An advertised 40-year option may be fully fixed and amortizing for 480 months, include an initial interest-only period, use a 40-year payment schedule with an earlier balloon, or reset after a shorter fixed period. Those are materially different loans. FastTrack DSCR compares the full structure—not merely a “40-year” label.
Read the 40-Year DSCR Market Intelligence report →
Business-purpose financing • Non-owner-occupied properties • Programs vary by lender and state
Compare the Payment and the Full Loan Term
A 40-year DSCR loan may reduce required monthly debt service, improve qualifying DSCR, and preserve rental-property cash flow.
Separate the four terms in every quote:
- Loan term: when the remaining balance must be repaid.
- Amortization: the schedule used to calculate principal-and-interest payments.
- Fixed-rate period: how long the interest rate stays unchanged.
- Interest-only period: when scheduled payments do not reduce principal; confirm the payment afterward.
A loan can use 40-year amortization and still mature earlier, leaving a balloon balance. For a comparison, provide your requested amount, rent, taxes, insurance, expected holding period and any existing payoff or prepayment terms.
40-Year Structures We Can Review
The right comparison includes the fixed-rate period, maturity date, interest-only term, amortization after interest-only, balloon or reset risk, monthly payment, DSCR impact, total interest, principal reduction, prepayment provisions, leverage, and reserves.
True 40-Year Fixed
A genuine 40-year fixed loan keeps the stated rate for the full 40-year term and fully amortizes over 480 months. Payments are generally lower than a comparable 30-year structure, though principal is repaid more slowly.
40-Year Fixed With Interest-Only
Some 40-year fixed programs begin with an interest-only period and then amortize the balance over the remaining term. The initial payment can be lower, but the payment increases when principal repayment begins.
40-Year Amortization & Balloon Structures
Some loans calculate payments using a 40-year amortization schedule but mature, balloon, or reset earlier. This may lower the scheduled payment without providing a true 40-year fixed-rate commitment.
INSIDE LENDERMATCH
See the effect of a different loan term
LenderMatch helps us explore term alternatives alongside the original scenario. We can review estimated payment and coverage changes with you, then obtain current lender pricing for the structures worth considering.
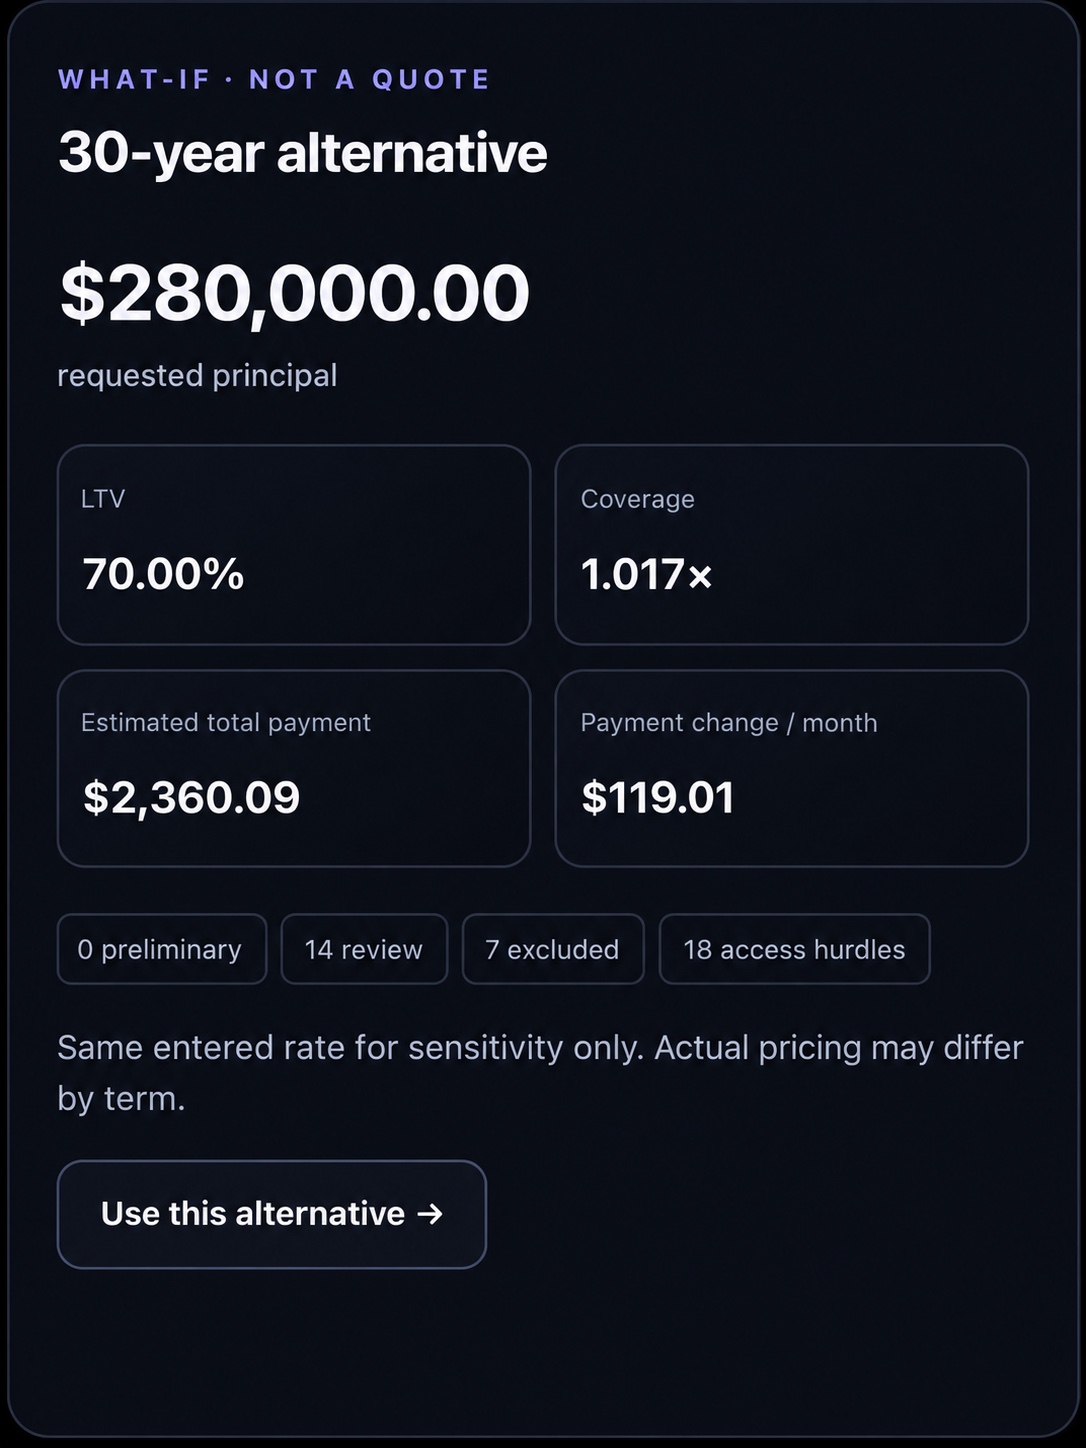
Readable version of the illustration: the pictured 30-year alternative uses a $280,000 requested principal, 70.00% LTV and 1.017× coverage. It displays an estimated total payment of $2,360.09 and a monthly payment change of $119.01.
This is a hypothetical sensitivity comparison using the same entered rate, not a quote, approval or funded transaction. Actual pricing can differ by term; the image’s status counts do not establish current lender availability. See the separate dated quote comparison for an example where both rate and amortization differed.
What Lenders Evaluate
- Full loan term, maturity date, and fixed-rate period
- Interest-only duration and payment after the IO period
- Amortization schedule, balloon payment, and rate-reset provisions
- Qualifying DSCR and the payment used for underwriting
- Total interest, principal reduction, and refinance risk
- Credit, LTV, reserves, loan size, property type, and prepayment terms
The Practical Trade-Off
A longer amortization term can improve monthly cash flow and DSCR, but it normally means slower principal reduction and greater total interest if the loan is held to maturity. Interest-only and balloon structures add payment-change or refinance risk.
The lowest opening payment is not automatically the lowest-cost—or lowest-risk—loan.
Why Investors Use FastTrack DSCR
Broader Lender Search
We compare specialty lenders offering 40-year DSCR structures and separate true long-term fixed options from loans using only 40-year amortization or an interest-only feature.
Scenario-Level Matching
Rate structure, term, amortization, interest-only period, balloon risk, DSCR, credit, leverage, reserves, property type, and exit strategy are evaluated together.
Straight Answers
You receive a practical comparison of monthly payment, DSCR, rate, amortization, interest-only terms, balloon or reset provisions, total interest, principal reduction, fees, and prepayment penalties.
40-Year DSCR Loan FAQs
It is a business-purpose rental-property loan with an interest rate fixed for the entire 40-year term and a balance scheduled to be fully repaid over 480 months, unless it includes a clearly disclosed interest-only feature.
Potentially. A lower required monthly payment may improve the property’s DSCR. Lenders still apply their own qualifying-payment method, minimum DSCR, credit, LTV, reserve, and property guidelines.
No. A loan can use a 40-year amortization schedule to calculate payments but mature or balloon sooner. The note’s maturity date, fixed-rate period, and balloon provisions determine the actual commitment.
Yes, some programs offer an initial interest-only period followed by amortizing payments for the remaining term. Borrowers should review the payment increase and the amortization period that begins afterward.
With the same balance and interest rate, spreading principal over 40 years generally lowers the required amortizing payment. Actual savings depend on rate, fees, interest-only features, and how long the loan is held.
Potential benefits include lower monthly payments and improved cash flow. Trade-offs can include slower equity buildup, more total interest, higher pricing, limited lender availability, payment changes after interest-only, or balloon and refinance risk.
The Label Matters. The Amortization Schedule Matters More.
Let us compare the complete 40-year structure against available 30-year alternatives. The right loan should improve usable cash flow while keeping future payment changes, refinance exposure, and long-term cost within the investor’s plan.
Related guides: 30-year vs. 40-year DSCR loans · Standard purchase and refinance · Rental-income coverage · All loan programs.
FastTrack DSCR provides business-purpose financing for non-owner-occupied investment properties. Program availability, rates, leverage, documentation, and approval are subject to lender guidelines and underwriting.