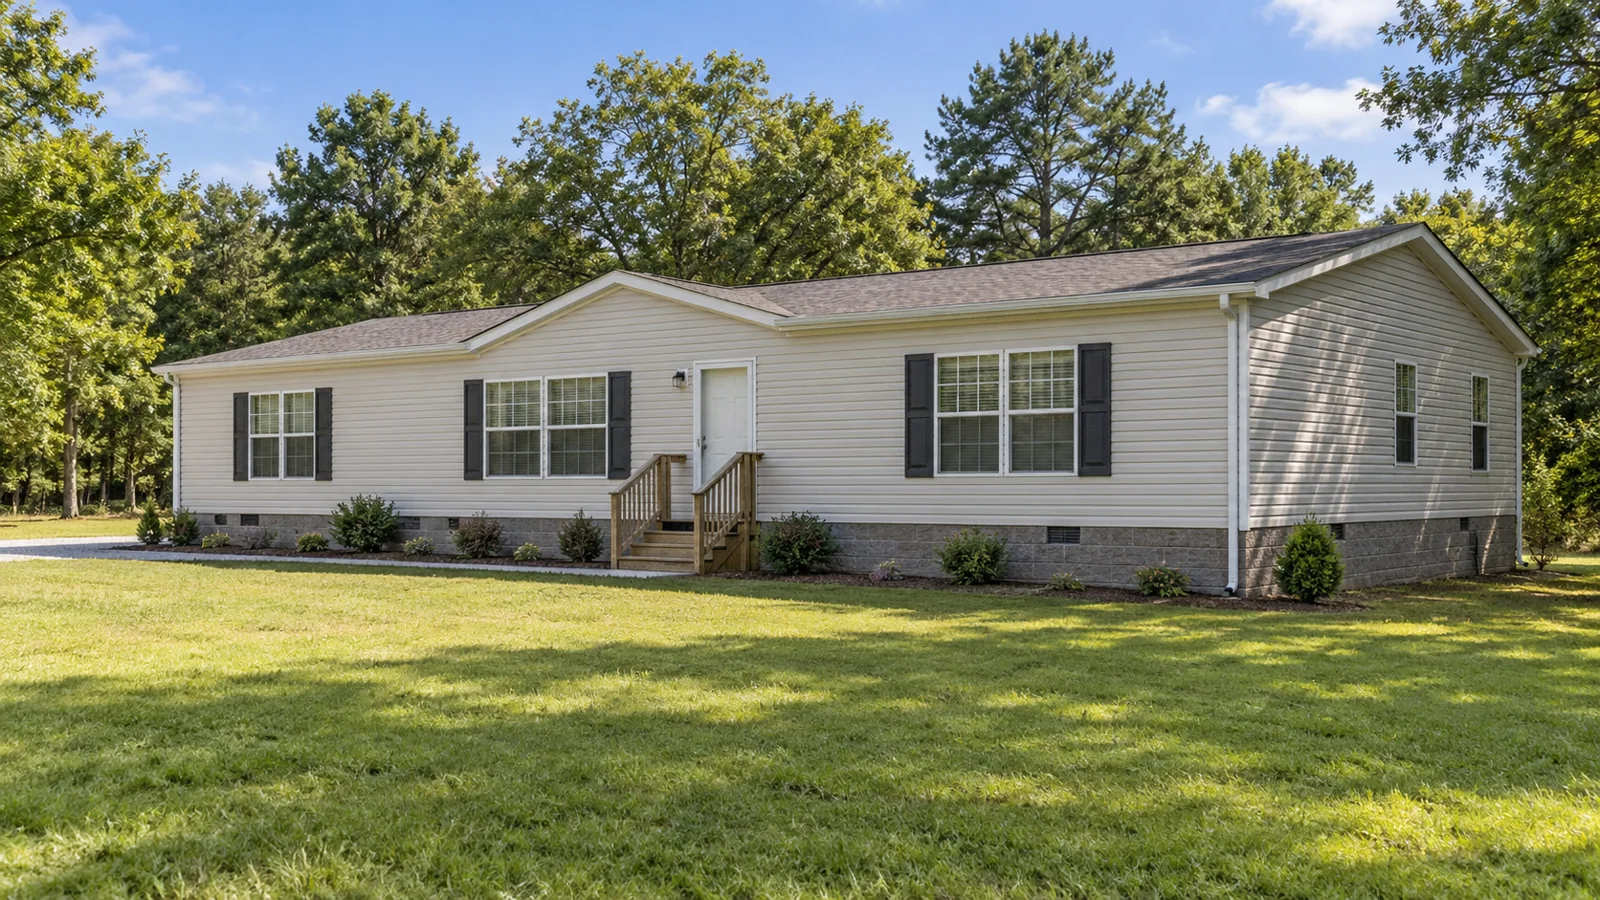
Illustrative AI-generated property; not a funded borrower property.
Specialty financing for real estate investors
DSCR Loans for Double-Wide Rental Homes
Own or plan to buy a double-wide manufactured rental home with land? FastTrack DSCR can review your property and financing goal against available lender programs. We check the home, foundation, title, land and state requirements before discussing loan options.
Read the Manufactured-Home DSCR Market Intelligence report →
Choose Manufactured Home on the quote form. Use Anything Else We Should Know for this preparation checklist:
- Year built and double-wide configuration; available HUD documentation.
- Who owns the land and whether the home is titled as real property.
- Permanent-foundation details and any existing certification.
- Purchase, refinance or cash-out goal, current rent and estimated value.
Flag any unknowns so we can check property eligibility before you order reports.
For investment properties only: double-wide homes on borrower-owned land, permanently affixed and legally treated as real property. Home age, HUD documentation, location and lender requirements apply. Single-wide homes, owner-occupied homes, leased-lot and home-only chattel financing are outside this review.
FastTrack DSCR is an independent broker, not a direct lender. Availability varies by lender, property and state. A scenario review is not approval or a commitment to lend.
Business-purpose financing • Non-owner-occupied properties • Programs vary by lender and state
Finance Eligible Manufactured Homes as Rental Properties
The first question is usually not just DSCR. Lenders must determine whether the home is legally classified as real property, permanently affixed, titled correctly, and acceptable under the program’s age, foundation, acreage, condition, and appraisal rules.
Manufactured-Home Scenarios We Can Review
Manufactured-home eligibility varies significantly by lender. A financeable scenario commonly depends on HUD-code status, permanent foundation, land ownership, title treatment, home age and width, property condition, comparable sales, DSCR, credit, leverage, and reserves.
Purchase Financing
We can review purchases of eligible double-wide manufactured rental homes together with borrower-owned land. The home must meet the selected lender’s age, HUD-code, foundation, title, appraisal and other requirements. FastTrack DSCR does not offer single-wide financing.
Buying a home to deliver and install on land is different from purchasing a completed rental. Tell us if placement, foundation work or site work remains unfinished; the property’s completion status and requested costs need separate program confirmation.
Refinance & Cash-Out
Rate-and-term refinance and cash-out scenarios may be reviewed for eligible double-wide rental homes with owned land. Maximum leverage, seasoning, valuation and documentation depend on the lender and transaction. Do not assume immediate cash-out or a particular loan-to-value ratio.
Land-and-Home Transactions
Many programs require the manufactured home and borrower-owned land to secure one real-estate loan. Homes on leased land or chattel-only transactions generally require a different financing category.
INSIDE LENDERMATCH
One property. Every requirement considered.
Manufactured housing and leverage need to work together in the same lender’s program. LenderMatch helps us organize those requirements before we confirm property eligibility and available terms.
Can I Finance a Mobile Home Rental with a DSCR Loan?
Potentially, if the property meets a lender’s manufactured-home requirements. Borrowers often search for a “mobile home rental loan,” but the home’s legal classification, construction standard, title, foundation, and land ownership determine which financing category applies.
Manufactured Home with Land vs. a Home on a Rented Lot
A manufactured home permanently attached to borrower-owned land and legally treated as real property may fit a land-and-home DSCR mortgage. A home on a rented lot, or one financed as personal property only, is a different request. Do not assume that a lender offering manufactured-home mortgages also offers leased-lot or chattel financing.
Example: Similar Rent, Different Financing Eligibility
Hypothetical comparison: Two manufactured homes each rent for $1,400 per month. The first is permanently installed on land included in the purchase, with the title and foundation documentation available for review. The second sits on a leased park lot and is sold as a home-only transaction.
The same rent does not make these properties equally eligible for a DSCR mortgage. The first can be screened for land-and-home programs; the second needs a separate review of its financing category. Neither is approved based on rent alone.
For an initial review, gather the property state and address, year built, confirmation that the home is double-wide, owned-land details, title status, foundation documentation, purchase price or value, estimated rent and financing goal. Read our manufactured and mobile-home DSCR guide, explore rental coverage with the DSCR calculator, or ask us to review the home and land.
What Lenders Evaluate
- Real-property classification and title treatment
- Permanent foundation and any required engineer certification
- HUD labels, data plate, home age, width, and prior moves
- Land ownership, acreage, additions, and property condition
- Appraisal quality and comparable manufactured-home sales
- DSCR, rent support, credit, LTV, reserves, and seasoning
The Practical Trade-Off
Manufactured-home DSCR loans often have a smaller lender pool and tighter property overlays than standard single-family rentals. Some programs reduce maximum LTV, require stronger credit or reserves, or add foundation, appraisal, and title documentation.
Manufactured, modular, and mobile homes are not interchangeable classifications—the details matter.
Why Investors Use FastTrack DSCR
Broader Lender Search
We compare specialty DSCR lenders that will consider eligible manufactured homes instead of stopping at a broad property-type exclusion.
Scenario-Level Matching
Real-property status, foundation, title, land, home age and width, appraisal support, DSCR, credit, leverage, reserves, and transaction type are reviewed together.
Straight Answers
You receive a practical comparison of leverage, pricing, foundation and title requirements, appraisal standards, cash-out rules, reserves, fees, and prepayment provisions.
Manufactured-Home DSCR Loan FAQs
Yes, certain lenders offer DSCR financing for eligible non-owner-occupied manufactured homes. The property commonly must be legally classified as real estate, permanently affixed to an acceptable foundation, and titled with the land.
Manufactured homes are built to the federal HUD code established in 1976. “Mobile home” is often used informally, especially for older units. Modular homes follow state or local building codes and are usually underwritten differently.
Most real-estate DSCR programs expect the home to be permanently affixed. A lender may require a foundation inspection or engineer certification confirming that the installation meets applicable requirements.
Most manufactured-home DSCR mortgages finance a home attached to borrower-owned land as one real-estate asset. Leased-land and chattel-only transactions are different loan types with more limited options.
Potentially. Availability depends on the lender, home and land eligibility, seasoning, valuation, credit, DSCR, reserves, and maximum cash-out LTV.
Age rules vary. Homes built before the federal HUD-code effective date of June 15, 1976 are generally much harder to finance, and many lenders apply additional age, condition, width, or prior-move restrictions.
Manufactured Housing Needs the Right Lender Match
Let us review the home, land, title, foundation, valuation, and borrower profile before you spend time chasing a lender that does not finance the property type. The right program starts with an accurate classification.
Related guides: Can you get a DSCR loan on a manufactured or mobile home? · Credit-profile considerations · Standard rental-property loans · All loan programs.
FastTrack DSCR provides business-purpose financing for non-owner-occupied investment properties. Program availability, rates, leverage, documentation, and approval are subject to lender guidelines and underwriting.