FASTTRACK DSCR · INVESTOR GUIDE

Can You Get a DSCR Loan on a House With an ADU?
A second rental unit could improve your financing numbers. But will the lender count its income?
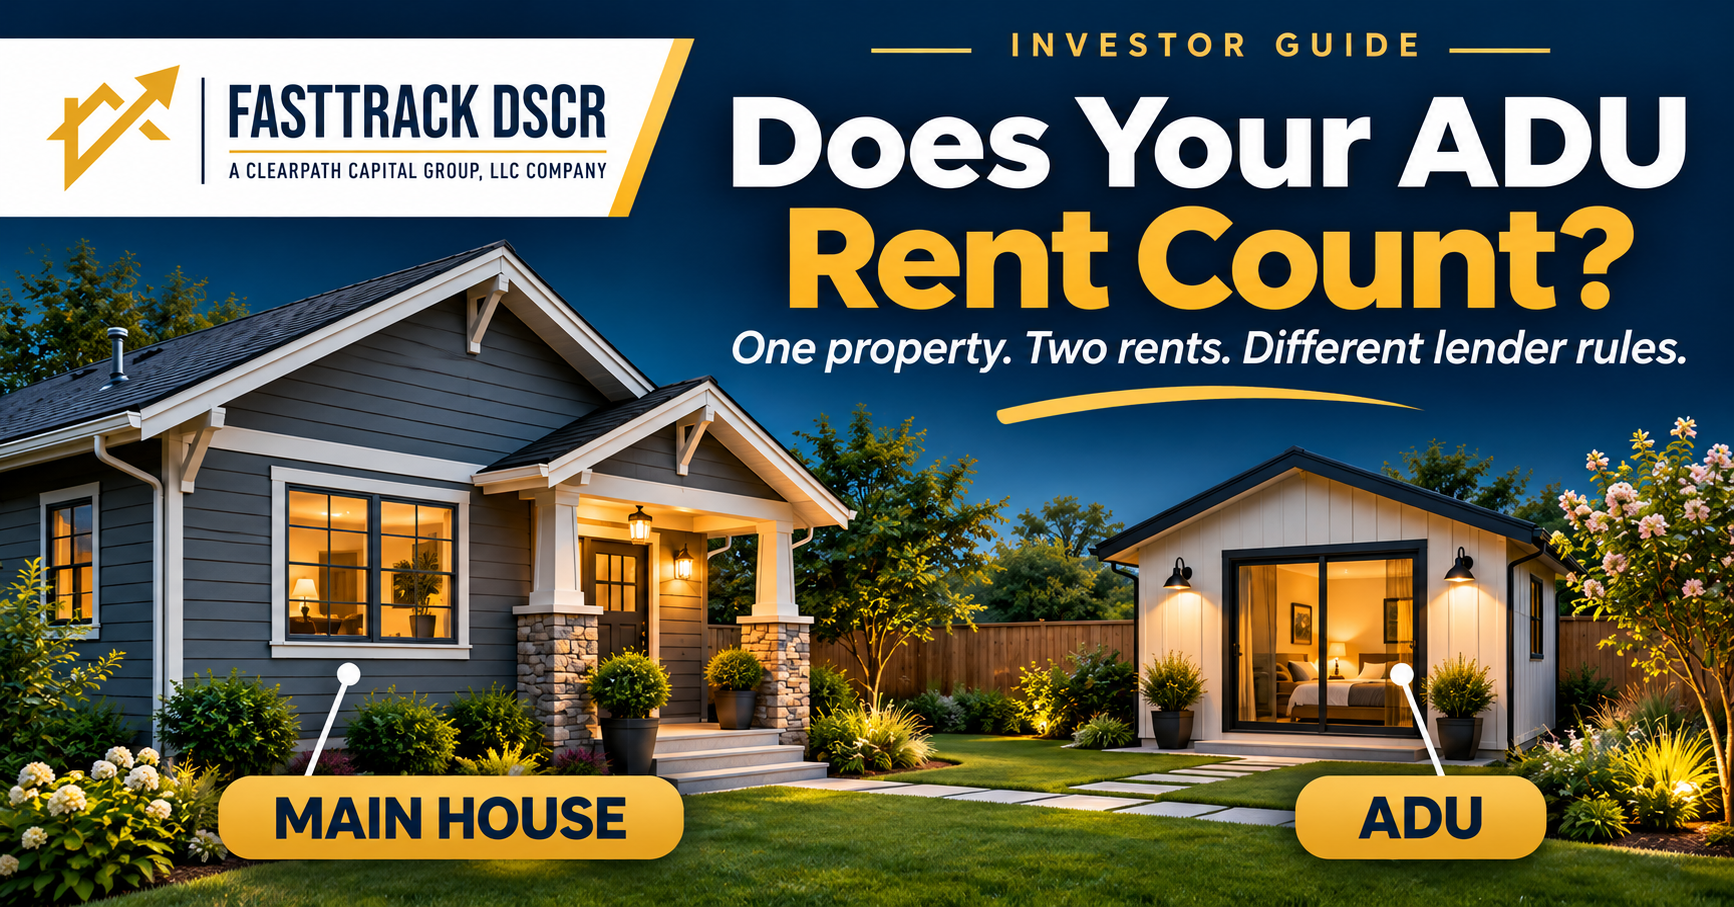
Picture a rental house with a detached backyard apartment. The main home rents for $1,800 per month, and the smaller unit brings in another $950. From an investor’s perspective, that’s $2,750 in monthly rental income.
But what if your DSCR lender only recognizes the main house? That difference could change your financing options. The real question isn’t simply whether the property has two rentable spaces. It’s whether the lender recognizes the accessory dwelling unit (ADU), accepts its income, and can support both with the required appraisal and documentation.
The quick answer: Yes, some DSCR lenders allow ADUs
Some DSCR lenders finance eligible investment properties with accessory dwelling units and may include qualifying ADU rent when calculating debt service coverage. But the property itself being eligible and its additional rental income being eligible are two separate decisions.
A lender may accept the home as collateral but exclude the extra rent. Another may recognize both the main dwelling and an eligible ADU, depending on its property standards, lease requirements, and appraisal support. This is a reason to compare programs rather than assume one lender’s approach represents the market.
FastTrack reviews these differences through its standard DSCR purchase and refinance programs.
What qualifies as an accessory dwelling unit?
An ADU is a secondary residential living space associated with a primary dwelling. Examples include a detached backyard cottage, garage apartment, basement apartment, or attached in-law suite. What matters for financing is how that space is physically and legally classified.
A separately accessible bedroom isn’t automatically an ADU. A lender or appraiser may examine the unit’s cooking facilities, bathroom, living and sleeping space, permitted use, zoning status, and marketability. Requirements vary by jurisdiction and lender.
For example, AD Mortgage’s published April 2026 guidelines describe eligibility for certain one-unit properties with a single accessory unit, specify a functional kitchen and bathroom, and address appraisal and unpermitted-unit conditions. Those conditions belong to that lender’s program and should not be treated as industry-wide rules.
How do lenders calculate rental income from an ADU?
Many residential business-purpose DSCR programs calculate coverage by dividing the lender’s accepted monthly rent by the property’s proposed monthly principal, interest, taxes, insurance, and association dues (PITIA).
COMMON RESIDENTIAL DSCR FORMULA
DSCR = Lender-accepted monthly rent ÷ Monthly PITIA
An ADU’s projected, appraised, or actual rent is not automatically accepted by every lender.
Buying a property with an existing ADU
On a purchase, a lender may consider market-rent support for the main home and the accessory unit separately. A signed lease, the unit’s condition, its legal status, and appraisal comparables may affect whether the secondary rent is counted.
As one concrete lender example, AD Mortgage’s April 16, 2026 DSCR guidelines say that, for purchases, the lower of eligible ADU market rent on the specified rental schedule or actual rent may be used. That is not a universal rule across DSCR lenders.
Refinancing a rental property with an ADU
For an existing rental, a track record of ADU income can help, but documentation standards vary. Some lenders require an executed lease and evidence that rent has actually been received.
The same AD Mortgage guidelines describe a refinance approach involving ADU rent supported by an existing lease and two months of documented receipts. Confirm the current version of the relevant lender’s guidelines before applying; a different program may accept different evidence or decline to count the ADU income.
The numbers: Why ADU income can change the deal
Consider the following hypothetical purchase or refinance. Assume the lender uses the main-house rent when ADU income is not eligible, and both rents when it is accepted.
| Estimated monthly item | Amount |
|---|---|
| Main house rent | $1,800 |
| ADU rent | $950 |
| Combined rent | $2,750 |
| Proposed PITIA | $2,200 |
| DSCR without ADU rent | 0.82 |
| DSCR with eligible ADU rent | 1.25 |
Without the ADU’s income, the calculation is $1,800 ÷ $2,200 = 0.82. If the lender accepts the full $950 of ADU rent, it becomes $2,750 ÷ $2,200 = 1.25. That shift may make a meaningful difference in the financing options available.
A higher DSCR does not automatically establish positive cash flow after vacancy, repairs, management, and other costs. Evaluate both the underwriting ratio and your investment cash flow. You can test the coverage calculation using the FastTrack DSCR Calculator. If the ratio still falls below 1.00, low-DSCR or no-ratio financing may be worth exploring.
Five things to verify before applying
- Property classification: Is the secondary space an eligible ADU under local standards and the lender’s property guidelines?
- Permits and occupancy: Is it complete, legally usable, and compliant with applicable zoning or nonconforming-use rules?
- Rental documentation: Will the lender rely on market rent, an executed lease, documented rent receipts, or another method?
- Appraisal support: Can the appraiser separately identify the ADU and support its marketability and eligible rent?
- Loan structure: Is this a purchase or refinance, and will ADU income affect DSCR, permitted leverage, reserves, or property eligibility?
Addressing these questions early is better than making an offer based on rental income the eventual lender may not recognize.
What changed with ADU appraisals in 2026?
Fannie Mae’s 2026 appraisal updates recognize more ADU configurations within its redesigned Uniform Appraisal Dataset (UAD) 3.6 framework. For applicable agency submissions, the redesigned appraisal process replaces older standalone reporting practices and captures more structured property information.
The November 2, 2026 UAD 3.6 mandate applies to new agency appraisal submissions, with a temporary exception process for eligible lenders. Fannie Mae reports that approved lenders may continue some older-format submissions during the transition period.
Important: Fannie Mae agency appraisal policies do not automatically determine the guidelines for non-agency, business-purpose DSCR loans. A DSCR lender may still specify Form 1007, leases, rental history, or other documentation under its own requirements.
The practical step is to ask what appraisal format and ADU income evidence your chosen DSCR program currently requires.
Can you finance an ADU that hasn’t been built yet?
Financing a completed rental property with an existing ADU is different from borrowing to construct a new backyard apartment. A standard DSCR purchase or refinance generally should not be assumed to fund proposed construction or count hypothetical future rent.
An investor may need a construction or renovation financing option during the build and a separate DSCR evaluation after the ADU is complete and eligible. Financing the ADU separately from its underlying property also is not the ordinary structure for a first-lien residential DSCR mortgage.
Frequently asked questions
Can an Airbnb ADU count toward DSCR?
Possibly with some specialty programs, but it is not automatic. Short-term rental income has different underwriting methods and documentation requirements from long-term lease income. Some lenders expressly exclude short-term ADU income even when they permit eligible long-term ADU rent. Confirm program-specific rules and local STR restrictions.
Can I live in the main home and rent out the ADU with a FastTrack DSCR loan?
FastTrack’s DSCR options are designed for business-purpose, non-owner-occupied investment properties. An owner who intends to live in the main dwelling would generally need to explore an owner-occupied financing program instead.
Does a detached ADU automatically turn the house into a duplex?
No. A second living space does not automatically change the property’s legal unit classification. The appraiser and lender must evaluate how the property is classified and whether that classification meets the selected program’s requirements.
Will every DSCR lender count the ADU rent?
No. Property eligibility, appraisal requirements, accepted rent, and documentation vary. A lender can approve the property type while excluding the ADU’s rental income from its DSCR calculation.
Bottom line: Don’t assume the second rent check counts
An eligible and documented ADU can improve a rental property’s earning potential. With a lender that accepts the additional income, it may also improve the qualifying DSCR. But assuming that every lender counts it can overstate your borrowing options.
FastTrack uses LenderMatch™ to compare the complete property, income evidence, and financing scenario—not just the advertised interest rate.
Have a rental property with an ADU?
Tell us about the main house, the ADU, rental income, and your financing goal. We’ll review the complete scenario against available lender programs to identify suitable options.
Review My House + ADU Scenario →
Full quote intake • Business-purpose investment properties • Subject to lender approval
This information is educational, not a commitment to lend. Property eligibility, qualifying rent, DSCR, rates, fees, LTV, reserves, and documentation requirements vary by lender, state, and transaction.
Keep Exploring
Underwriting references: AD Mortgage — Non-QM Loan Eligibility Guidelines (April 16, 2026); Fannie Mae — Appraiser Update (March 2026); Fannie Mae — UAD 3.6 transition policy. Lender-specific guidelines may change.