Can You Get a DSCR Loan on a House With an ADU?
Can a house with an ADU qualify for a DSCR loan? Learn when accessory dwelling unit income counts, how appraisals and leases affect underwriting, and which questions to ask.
FastTrack DSCR is an independent business-purpose mortgage broker. We compare multiple lenders for rental-property purchases, refinances and specialty scenarios—helping you find competitive terms and a program that fits your deal. Eligible options include up to 85% LTV for purchases and rate-and-term refinances, and up to 80% LTV for cash-out, subject to program requirements.
Purchase & Refinance • Standard & Specialty DSCR • Rental Properties • Nationwide Programs
Introducing LenderMatch™
FastTrack DSCR is built for both sides of the DSCR market: clean, straightforward files where pricing and terms matter, and more difficult scenarios where lender guidelines matter just as much. We compare multiple programs instead of assuming one lender is automatically the best fit.
For strong-credit, strong-DSCR purchases and refinances, we compete on rate, fees, LTV, prepayment structure, and overall terms. When a deal falls outside the standard box, our broader lender network gives us more ways to find a workable solution.
Competitive options for clean, straightforward DSCR loans—plus specialty programs when the deal needs more flexibility.
Eligible DSCR options reach up to 85% LTV for purchases and rate-and-term refinances, and up to 80% for cash-out. Eligible purchases may require as little as 15% down before closing costs and reserves. We compare rates, fees, leverage and prepayment terms for the complete scenario.
When the deal falls outside the standard box, our lender depth becomes even more valuable. We can review low-FICO and no-score, low-DSCR and no-ratio, high-LTV, STR/Airbnb, manufactured-home, PadSplit and co-living, second-position loans and investor HELOCs, blanket/portfolio, and 40-year DSCR scenarios.
Practical answers for real-estate investors comparing DSCR programs, qualification rules, and financing strategies.

Can a house with an ADU qualify for a DSCR loan? Learn when accessory dwelling unit income counts, how appraisals and leases affect underwriting, and which questions to ask.

Do DSCR lenders use gross rent or net income? See the PITIA formula, why lender ratios differ, and how a property can qualify yet lose money.
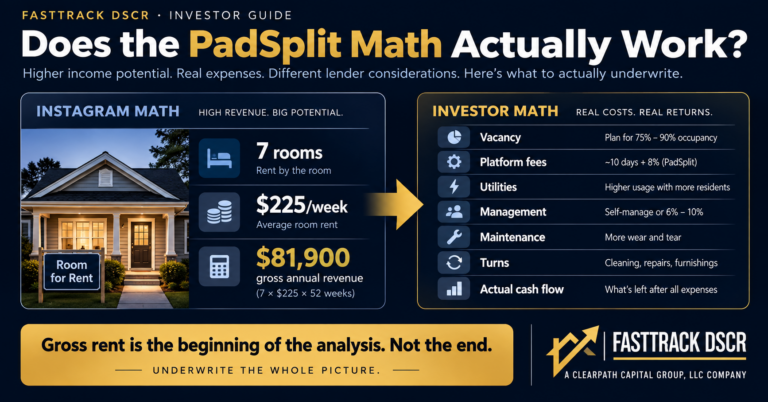
Is PadSplit profitable? See a realistic seven-room rent-by-the-room example with occupancy, platform fees, operating costs, cash flow, and DSCR lender requirements.
FAQs
No. We work with programs for experienced investors and borrowers purchasing their first investment property. Available leverage, pricing, and reserve requirements may vary by experience.
Our core expertise is long-term rental financing. When a property needs renovation first, we can also review bridge or fix-and-flip options and help plan a DSCR refinance after stabilization.
Conventional loans focus heavily on personal income and debt-to-income ratios. DSCR loans are business-purpose mortgage loans that generally qualify primarily through rental income and property cash flow, while credit, reserves, value, and other lender guidelines still apply.
Available structures may include 30- or 40-year terms, fixed or adjustable rates, and interest-only periods. Options depend on the lender, property, transaction type, and borrower profile.
Credit reporting varies by lender and program. Many business-purpose DSCR loans may not appear on personal credit reports, but we confirm the reporting treatment for each specific option before you proceed.