Low-FICO & No-Score DSCR Market Intelligence — October 2026
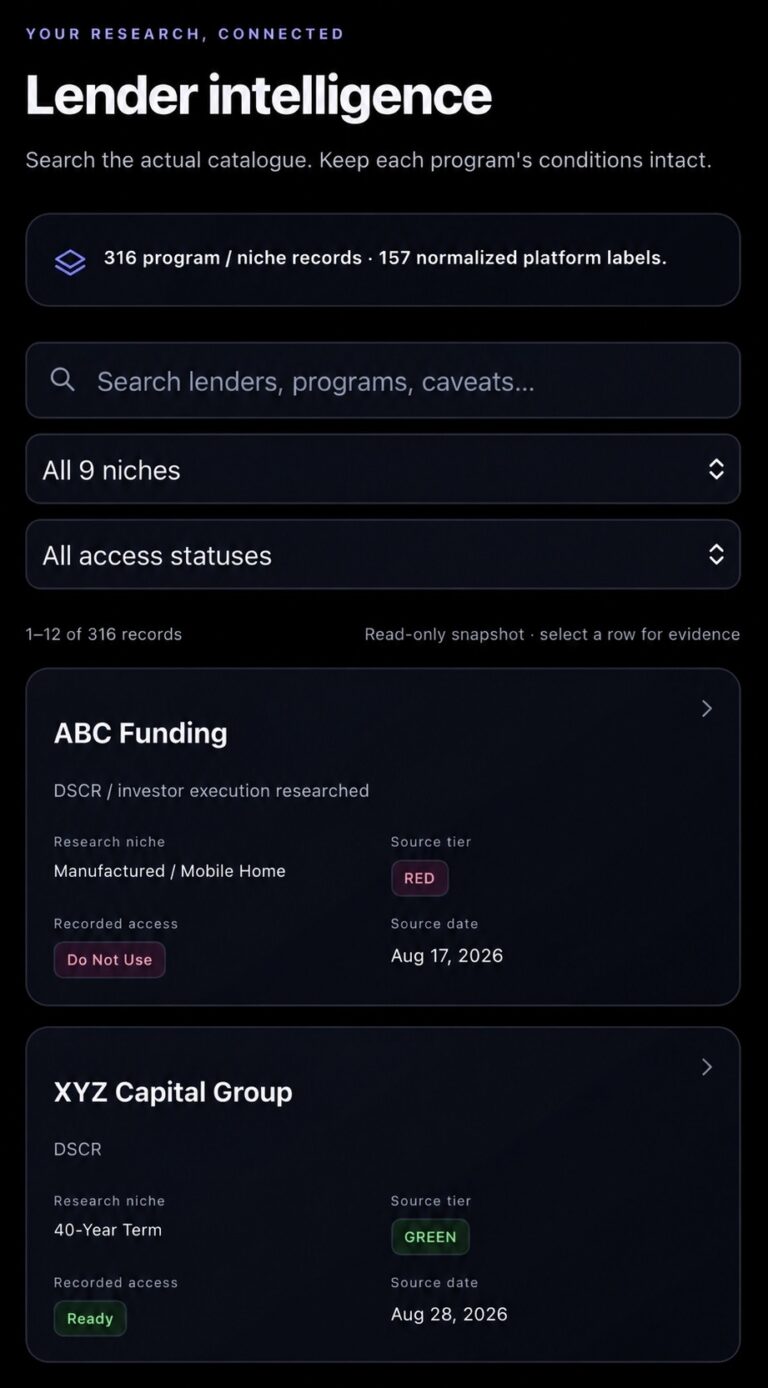
FastTrack LenderMatch research explains the difference between low-FICO DSCR, no-minimum-FICO marketing and genuine no-score underwriting.


FastTrack LenderMatch research explains the difference between low-FICO DSCR, no-minimum-FICO marketing and genuine no-score underwriting.
FastTrack LenderMatch research shows how manufactured-home DSCR eligibility changes by home type, cash-out purpose, seasoning, title, foundation and lender channel.
Explore specialty DSCR lending research, including credit, rental income, leverage, property type and loan structures that can change an investor's financing options.
DSCR GUIDE Can You Get a DSCR Loan on a Single-Wide Manufactured Home? Single-wide manufactured homes can be eligible with select DSCR lenders, but the lender pool is narrower and the property has to satisfy real-property, title, foundation, condition, age,…
A 0.90 DSCR does not always end the financing conversation. Learn how low-DSCR programs, LTV, credit, reserves and loan structure affect eligibility.
Some DSCR loans are available with no prepayment penalty. Learn how zero-prepay options can affect rate, points, leverage and lender choice.
Can you get a 75% LTV DSCR cash-out refinance? Learn which borrower, property and seasoning factors determine whether 75% leverage is realistic.
Learn what affects a manufactured-home DSCR cash-out refinance, including real-property status, title, foundation, seasoning, valuation, credit and LTV.
A 620 credit score can fit certain DSCR programs. Learn how LTV, DSCR, reserves, property type and loan purpose affect eligibility.
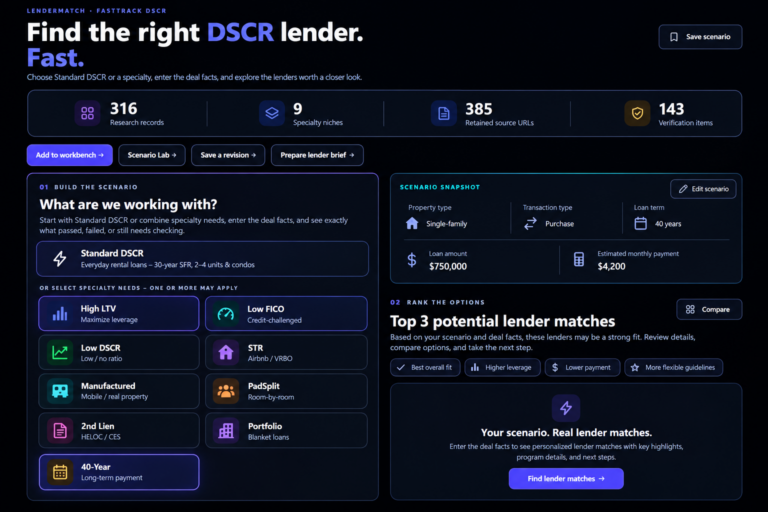
FastTrack built LenderMatch to help investors find better-fit DSCR lenders based on the complete deal—not just an advertised rate.